Key takeaways
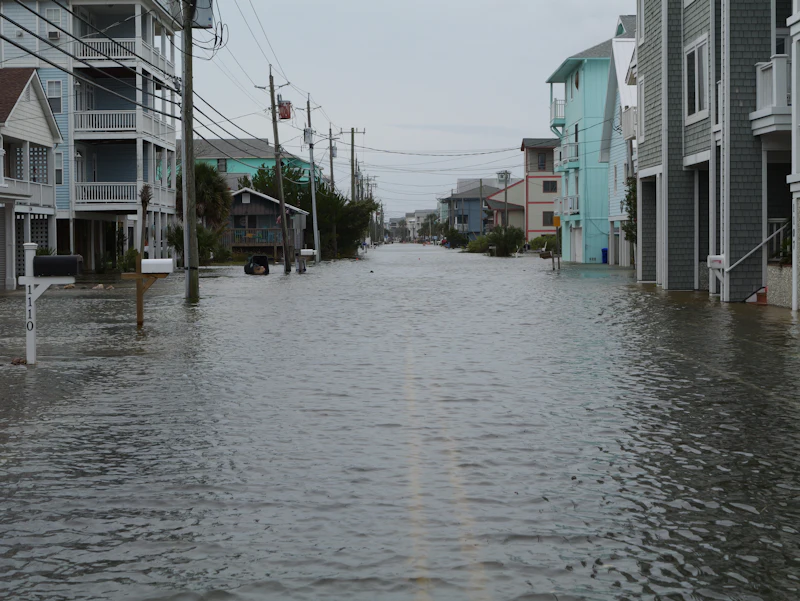
- In plain terms, a flood is an excess of water on land that is normally dry. A flood policy covers direct physical losses, damage, or loss caused by a flood.
- Contents coverage can be bought separately from building coverage.
Tools and comparisons

NFIP vs. private flood insurance
FEMA manages the NFIP; Pennsylvania says private flood insurers are licensed and regulated by the state, with more protection than non-admitted insurers.
NFIP flood coverage limits
NFIP building policies for homeowners cover up to $250,000 of flood damage, and contents policies cover up to $100,000.
Who can buy NFIP flood insurance
- Flood insurance is available to anyone living in one of the 22,600 communities that participate in the NFIP.
- Homes and businesses in high-risk flood areas with mortgages from government-backed lenders are required to have flood insurance.
- There is typically a 30-day waiting period before an NFIP policy takes effect, unless the coverage is required by a government-backed lender or is related to a community flood map change.
- The NFIP Dwelling Policy Form is issued to homeowners, residential renters, condominium unit owners, and owners of residential buildings with two to four units.
How the NFIP defines a flood
In plain terms, a flood is an excess of water on land that is normally dry. A flood policy covers direct physical losses, damage, or loss caused by a flood.
Advertisement
From this site
Each statement is tied to a dated passage of an official source.
What building and contents coverage include
Contents coverage can be bought separately from building coverage.
- Building coverage includes the insured building and its foundation.
- Building coverage includes refrigerators, cooking stoves, and built-in appliances such as dishwashers.
- Contents coverage includes personal belongings such as clothing, furniture, and electronic equipment.
- Contents coverage includes certain valuable items such as artwork, furs, and jewelry, up to $2,500.
What flood insurance does not cover
- Damage from moisture, mildew, or mold that the property owner could have avoided is not covered.
- Coverage in a basement is limited.
Advertisement
From this site
Each statement is tied to a dated passage of an official source.
How claims are paid
Replacement Cost Value is the cost to rebuild with the same kind of material and construction, with no deduction for depreciation. Actual Cash Value is the cost to replace insured property minus physical depreciation. A building claim is settled at replacement cost, up to the coverage purchased, if the building coverage is within 80% of the home's replacement cost and the home is your principal residence. Contents claims are always paid at Actual Cash Value.
Increased Cost of Compliance coverage
Policyholders in high-risk flood areas may receive up to $30,000 to help bring a home or business into compliance with local floodplain management rules. Substantial damage means the community finds that repairs will cost 50 percent or more of the building's pre-damage market value. An ICC claim is adjusted separately from the flood damage claim filed under the Standard Flood Insurance Policy.
Common questions
Does flood insurance cover cars?
Most self-propelled vehicles, such as cars and their parts, are listed among the losses a flood policy does not cover.
What this page does not cover
This page explains the federal flood program and does not compare insurance companies.
Sources
- Flood Insurance, Federal Emergency Management Agency (FEMA). Read November 17, 2026.
Flood insurance is a separate policy that can cover buildings, the contents …
- NFIP Summary of Coverage, FEMA, National Flood Insurance Program. Read November 17, 2026.
Actual Cash Value (ACV) is the cost to replace insured property less …
- Increased Cost of Compliance Coverage, Federal Emergency Management Agency (FEMA). Read November 17, 2026.
Flood insurance policyholders in high-risk flood areas (also known as special flood …
- National Flood Insurance Program Underwriting Forms, Federal Emergency Management Agency (FEMA). Read November 17, 2026.
The Dwelling Policy Form is issued to homeowners, residential renters and condominium …
We cite a few words and link to the official text. Full copies are kept as internal records, not republished.
Every statement on this page is tied to an official source that we copied and dated. We do not sell insurance and we do not recommend companies. Editorial policy, Data sources.
We don't sell insurance and rank no insurer. How we make money